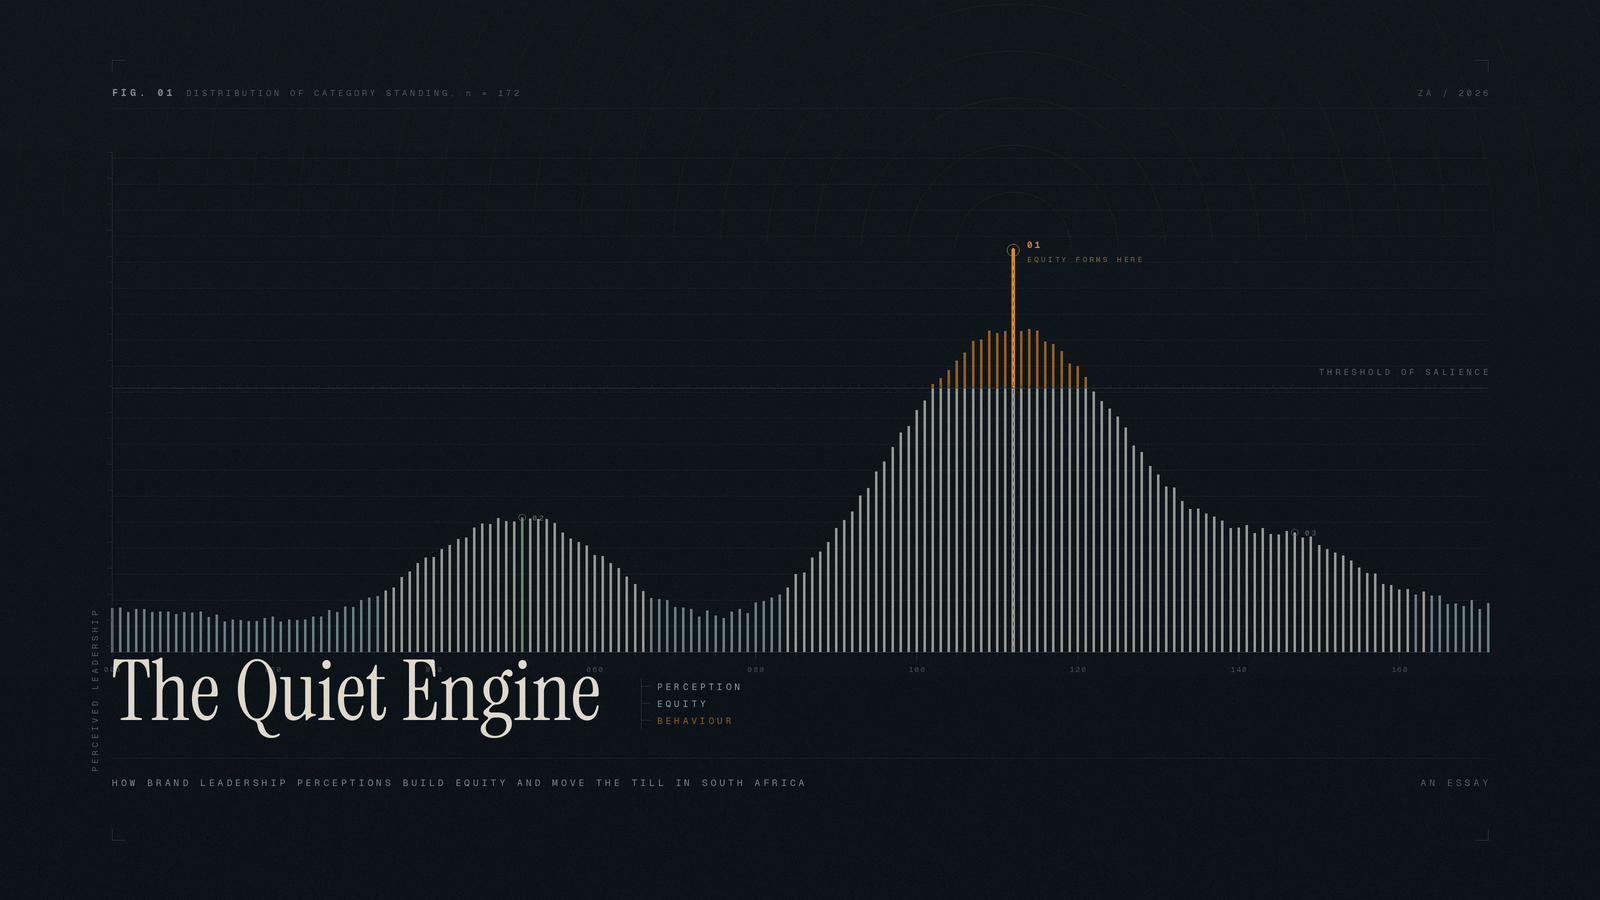
There is a proposition that sits near the centre of modern brand strategy, and it deserves a proper local interrogation: when consumers come to see a brand as the leader in its category, that perception feeds brand equity, and that equity eventually shows up in what people actually buy, how often, and at what price.
It sounds almost too neat. Leadership is perceived, equity is built, tills ring. But the mechanism is real, it is measurable, and in a market like ours it behaves in ways that differ meaningfully from what the textbooks written in London or Chicago would predict.
What "brand leadership perception" actually means
Brand leadership in the consumer's mind is not the same thing as market share on a Nielsen report. It is a belief, held loosely or firmly, that a brand sits at the front of its category. Research going back to Aaker's work on brand equity measurement treats it as a composite of roughly four judgements:
- Quality superiority. The sense that this brand does the job better.
- Popularity or market presence. The sense that lots of people, and specifically people like me, use it.
- Innovativeness. The sense that this brand moves first and the others copy.
- Value credibility. The sense that the brand is honest about what it charges relative to what it delivers.
A consumer does not need all four. Shoprite is not perceived as innovative in the way Discovery is, and Woolworths is not perceived as a value leader in the way PEP is. What matters is that at least one or two of these judgements are strongly held and are attached to the brand rather than to the category.
The critical point for practitioners is that these are perceptions, not facts. A brand can be the volume leader and not be perceived as the leader. A brand can be perceived as the leader long before its share justifies it. That gap, in either direction, is where marketing money either earns its keep or evaporates.
Why the perception converts into equity
Three mechanisms do most of the work.
Signalling and risk reduction. Information economics tells us that brands function as credible signals in markets where consumers cannot verify quality before purchase. A brand that is perceived as the leader has, in the consumer's reasoning, more to lose from disappointing people. That perceived hostage to fortune makes the signal credible. The practical result is a lower perceived risk of purchase, and lower perceived risk translates directly into higher willingness to buy and higher willingness to pay.
Cognitive economy. Choosing is expensive. A leadership perception is a shortcut that lets a shopper resolve a decision in under two seconds in front of a shelf. This matters more than marketers usually admit, because most category decisions are low involvement even when the category is expensive.
Social validation. The popularity component of leadership is not vanity. It carries information. If most people around me use it, the odds that it is defective are low, and the social cost of choosing it is near zero. In collectivist purchasing contexts, and South Africa has many of them, this dimension does disproportionate work.
Together these mechanisms build the components of consumer-based brand equity that we can actually measure: awareness and salience, perceived quality, favourable associations, and loyalty. Equity, in turn, is the reservoir that funds behaviour.
The South African amplifiers
Here is where the general theory needs local calibration. Four features of this market make leadership perceptions unusually powerful.
A constrained wallet makes mistakes expensive. When a household is stretching a limited grocery budget across a month, the cost of buying a washing powder that does not work is not a mild irritation, it is a real loss that cannot be absorbed. Risk aversion rises, and risk aversion is precisely the condition under which leadership signals pay off most. This is why the intuition that price-sensitive consumers are disloyal is so often wrong. Research from the township consumer space makes the point plainly: even in a highly price-sensitive market, consumers will pay more for brands they trust and that they feel understand their needs. Consistent value rather than once-off promotions is what earns trust, and authentic community connection remains an advantage that pure price competition cannot replicate.
A trust deficit in institutions raises the value of trusted brands. South Africans have learned to be sceptical of large organisations. Consider the banking picture from township research: while 91% of respondents have bank accounts, only 37% feel their bank understands them, with high fees and branch distance the biggest frustrations. Into that gap walks a brand that is perceived to be genuinely on your side, and the perception compounds fast.
Informal and semi-formal trade rewards fast recognition. In a spaza shop, there is no category management, no facings strategy and no planogram. There is a shopkeeper deciding what to stock based on what will turn, and a customer asking for a brand by name. Leadership perception here is not a nice-to-have, it is the distribution strategy. Notably, since the spaza registration drive, 41% of township residents say they trust spazas more, and nearly half prefer shops run by an owner they know by name. Trust is being rebuilt at the outlet level, and brands that align with it inherit some of that credibility.
Group purchasing multiplies the effect. The stokvel is a distinctly South African mechanism that turns individual preference into collective commitment. Stokvel participation in townships has surged, with 71% of residents now belonging to at least one, up from 51% two years earlier, and grocery and funeral stokvels dominating. When a grocery stokvel commits to a December hamper, it is not one shopper choosing a maize meal, it is twenty households locking in a brand for a quarter. Committees converge on brands nobody will complain about, which is to say, brands perceived as leaders.
The evidence, read off local brands
Capitec is the cleanest case in the country. A bank that started in 2001 targeting the underserved built a leadership perception on simplicity, accessibility and honest pricing long before it had the balance sheet to match. It is now comfortably the largest bank in South Africa by clients, with just under 26 million active customers against an estimated 12 million for second-placed Standard Bank. The equity followed, and then got independently priced: Capitec ranks seventh globally for brand strength in Brand Finance's Banking 500 2026 report, with a Brand Strength Index score of 93.4 and an AAA+ rating, making it the strongest banking brand in South Africa. The behavioural payoff is main-bank switching, which is one of the stickiest and most valuable behaviours in any category.
Checkers shows how innovation leadership resets a brand's ceiling. Sixty60 did more than add a delivery channel. It converted Checkers from "the other big supermarket" into the brand that moved first and best. Sixty60 generated R11.9 billion in sales in the six months to December 2025, up 34.6%, and now accounts for more than 10% of Shoprite's South African supermarket sales, operating from roughly 875 stores with close to 10 000 drivers and past 100 million cumulative orders. The perceptual dividend is visible in independent measurement: Checkers was named the strongest brand in South Africa in 2026 with a Brand Strength Index score of 97 out of 100. The rival numbers are instructive rather than embarrassing. Pick n Pay's asap! grew online turnover 32.7% and reached more than 620 stores with over 2 500 drivers, but added only around 20 net store integrations in the year. Growing well while the leader extends its lead is a lesson in how leadership perception buys optionality.
Quality leadership funds pricing power. Woolworths Food was named South Africa's most recommended brand for 2026 with a recommendation score of 88.1%, ahead of Samsung on 86.2%, and Woolworths holds three of the top five positions in the ranking. Nobody argues Woolworths is cheap. That is the point. The perception of category quality leadership is what allows the price gap to persist rather than being competed away.
Value leadership is its own kind of leadership. PEP was ranked South Africa's fastest-growing brand in 2026, with brand value up 76% to R5.8 billion, driven partly by a rapid acceleration of its cellular offering. PEP leads on affordability credibility, and that perception is now being leveraged into adjacent categories, which is exactly what strong equity is for.
Cultural leadership can be earned without a media budget. South African streetwear labels GALXBOY and Redbat joined MaXhosa and Bathu in the Brand Africa 100 on organic consumer recall alone, with no pan-African media investment. These brands lead on a dimension the multinationals struggle to buy: cultural authorship. The behavioural consequence is a premium paid by consumers who, on a pure income basis, "should" be trading down.
Where the argument gets uncomfortable
An expert reading has to acknowledge three genuine problems with the thesis.
The causal arrow may point backwards. The Ehrenberg-Bass tradition would argue that perceived leadership is largely an output of penetration, not an input to it. Bigger brands are bought by more people, therefore more people report favourable attitudes, therefore the brand looks like a leader. On this reading, attitude follows behaviour. The honest position is that both are true and the relationship is reciprocal, which means marketers should be sceptical of any model that treats a rise in leadership scores as a leading indicator without testing whether distribution and availability moved first.
Leadership without warmth is fragile. Eskom leads its category by definition and holds no positive equity whatsoever. Telkom led fixed-line telephony for decades and converted almost none of it into durable preference. Perceived dominance in the absence of perceived benevolence produces resentment, not loyalty, and it collapses the moment an alternative appears. Leadership perception only builds equity when the leadership is seen as deserved.
Perceived leadership decays quietly. It is a lagging perception, which means a brand can lose operational leadership for two or three years before the perception catches up. That delay feels like resilience. It is actually the runway before impact. Several once-dominant South African retailers discovered this the hard way.
From equity to behaviour: what actually changes
If the leadership perception is real and earned, expect these behavioural shifts, roughly in this order:
- Consideration set entry. The brand becomes an automatic candidate rather than something that must be justified.
- Reduced promotional dependence. Volume holds up between price events, which is the single most valuable financial consequence of equity.
- Price premium tolerance. Consumers accept a gap and stop treating it as a reason to switch.
- Distribution pull. Independent traders stock it because customers ask for it by name, which lowers the cost of trade marketing.
- Category and channel extension. The brand earns the right to be believed in adjacent spaces, as Capitec has done in business banking and PEP in connectivity.
- Recovery capacity. When something goes wrong, and it will, consumers extend the benefit of the doubt.
Measuring it here
Global trackers are useful but thin on local nuance. For South African work, triangulate across several instruments rather than trusting one. The Ask Afrika Icon Brands benchmark is built on the TGI survey and is unusually broad, covering hundreds of categories across a large weighted national sample. It surveyed 24 760 consumers representing roughly 28.7 million adult South Africans, weighted using Statistics South Africa population estimates. Add the South African Customer Satisfaction Index for service categories, Brand Finance for the financial translation, and the various recommendation trackers for advocacy.
More importantly, build your own leadership battery into your tracker and keep the items constant for years. Four questions is enough: is this brand a leader in its category, is it growing, is it innovative, and is it the brand more people are choosing. Then model those items against actual purchase data rather than against stated intent. Stated intent in South Africa is optimistic by roughly the size of the gap between payday and month-end.
What this means for practitioners
Stop treating leadership as a claim to be asserted in advertising and start treating it as an inference to be engineered. Consumers infer leadership from evidence: from being first to solve a real problem, from being the brand everyone in the taxi is talking about, from being available when others are not, from behaving consistently when the economy is not.
The Sixty60 lesson is that solving a problem first and at scale creates a leadership perception that advertising cannot buy. The Capitec lesson is that being demonstrably on the customer's side in a category where trust is scarce compounds for twenty five years. The Bathu lesson is that cultural authorship is a leadership dimension the incumbents cannot outspend.
And the Eskom lesson is that leading a category and leading in the mind of the consumer are entirely different things.
The proposition holds. Leadership perceptions do build equity, and equity does move consumption. But in this market the perception has to be earned in ways that are visible, useful and locally legible, or it is just a claim on a billboard on the N1.