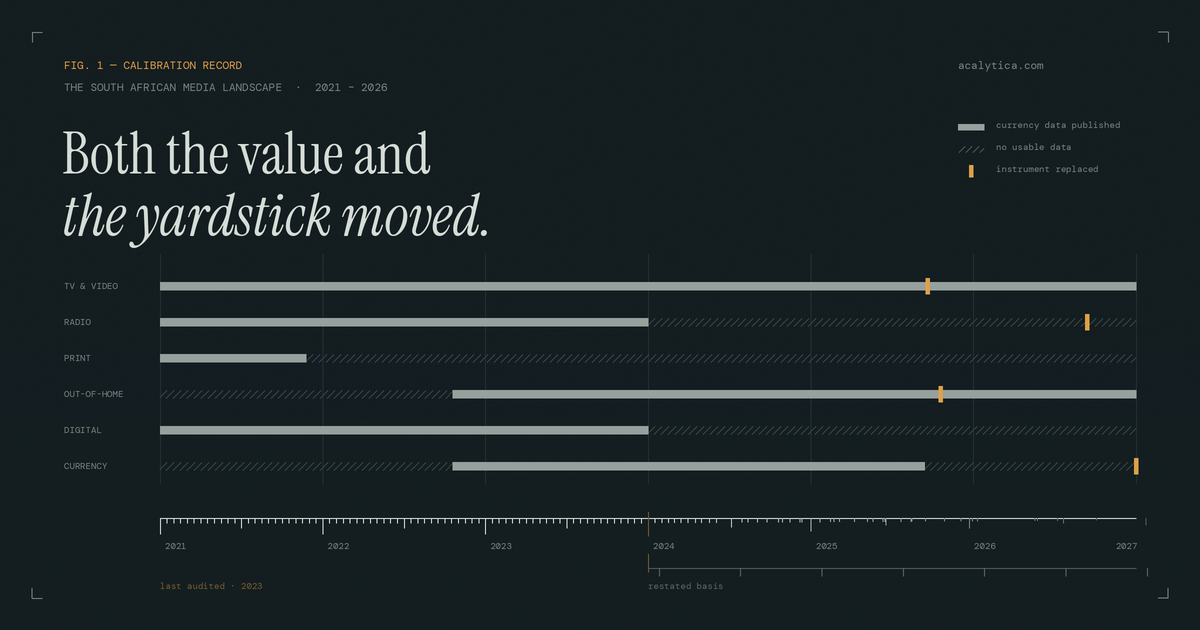
Acalytica has published a long, unusually careful account of what happened to South African media between January 2021 and August 2026. Its core argument fits in one sentence: the value of media inventory and the yardstick used to price it both moved at the same time. Legacy revenue fell faster than legacy inventory, and while that was happening, almost every audience currency the market trades on was torn up and rebuilt.
The report grades its own evidence, dates every figure, separates observed data from vendor forecasts, and keeps a register of places where credible sources flatly disagree. That discipline is itself a finding: on the public record, South Africa has no audited total-adspend figure after 2023, no channel split of traditional spend for any year in the window, no station-level radio currency since 2023, print readership resting on 2021 fieldwork, and a television currency that changes provider on 1 January 2027.
Here is what the report says, medium by medium.
Television: a shrinking base with a French owner
Broadcasting was the only regulated communications sector that contracted in 2025. ICASA's compulsory returns put total broadcasting revenue at R33bn (down 4.6%), with pay-TV subscribers falling below seven million for the first time in five years. Streaming contributed just 0.25% of broadcasting revenue, a quarter of one percent, while programme costs rose 7.6%. Costs are climbing into a shrinking base.
The defining event was Canal+ taking control of MultiChoice. The report is emphatic on the timeline because it is widely misreported: the offer went unconditional on 22 September 2025 and MultiChoice was delisted on 10 December 2025. Headlines claiming a July 2026 completion are recycled aggregation. The deal's public-interest conditions (a R26bn spend commitment, a moratorium on involuntary retrenchments) are already being tested, the Competition Commission is monitoring voluntary severance programmes and probing whether the Showmax closure breaches merger terms.
Showmax itself is described as an R8.7bn failure across three years of trading losses. It shut on 30 April 2026. Netflix moved into the gap within ten weeks by licensing an e.tv drama for continental distribution.
Two structural data problems follow. MultiChoice will never publish FY2026 results, and Canal+ does not disclose DStv South Africa subscriber numbers, so ICASA's lagging annual report is now the only independent series on the country's largest pay-TV operator. And a leaked DStv package restructure, splitting sport-weighted and entertainment-weighted tiers, was due for official announcement after the report's compilation date, so must be re-verified.
eMedia is the counter-case: e.tv became the biggest single channel in the country in prime time while the TV ad market fell 8.7%. It did so through cost and content discipline, not by building a streaming product. Even so, it proposed cutting 55% of eNCA's newsroom in August 2026, and launched Openview Stream in seven African countries while deliberately excluding South Africa because of domestic data costs.
The SABC's funding model is broken by its own executives' admission: a R253m net loss, TV licence collection at 15%, and no legislation on the table since the SABC Bill was withdrawn in November 2024. Analogue switch-off remains interdicted, with four provinces, roughly two-thirds of the population, still on analogue.
Radio: the most resilient medium, sold blind
Three-quarters of South Africans aged 15+ listen to radio weekly, averaging over five hours a day. It is the only truly national reach medium in a country where a fifth of people are offline. And it has traded without a published station-level currency for most of the period.
RAMS collapsed in 2020, was rebuilt under Ipsos using a modelled "synthetic" seven-day listener, and is now being rebuilt again by GfK. The last published station data covers January 2022 to December 2023; new data will be released only after Wave 4 validation, which closes in September 2026. The report's blunt instruction: any 2025 or 2026 station-level number you are shown is not currency data. The most-quoted station figure in the country, Ukhozi FM's 7.5 million weekly listeners, dates from 2018.
Community radio is quietly contracting. Counted from ICASA's own gazetted registers, community sound licences fell 23.7% between October 2021 and June 2026. Sentech has switched stations off over transmission debt, the MDDA's grants have nearly halved, and government's promise to direct 30% of advertising to community media has never been legislated. The Primedia sale process, first reported in July 2024, has no public resolution either way.
Print: three discrete collapses
Print didn't decline gradually. It fell in three events. In 2024, Media24 closed the print editions of Beeld, Rapport, City Press and Daily Sun (Soccer Laduma, often listed as closed, was sold and survives). In 2025–26, Financial Mail was sold to Apex Capital, City Press was slated for full closure, and Sekunjalo withdrew funding from Independent Media, seventeen national mastheads were licensed to a newly renamed company whose ownership is undisclosed.
The circulation numbers are stark. The Star's total circulation of 18,752 includes only 3,750 paid copies. Roughly 70% of the journalism workforce has gone since 2010. Trust in news fell to 50%.
What works, narrowly: paywalls (News24 and Netwerk24 have 221,872 subscribers, but page views fell a third in a year), membership (Daily Maverick's Insider model churns at 4.65% after five years), and custom publishing, the only growing print category, and one that is brand-funded rather than ad-funded.
Out-of-home: the one currency that improved, and a compliance crisis
OOH is the only traditional medium whose measurement got better. ROAD 2.0 launched in 2022 as a free joint-industry currency using Visibility Adjusted Contacts. But its digital formula was restated in October 2025 and the worked example moves a single panel from 122,500 to 300,682 people, a 2.5× restatement that will move CPMs. Transit, mall, airport and in-taxi media sit outside it entirely, measured only by the companies selling the space.
The sharper finding is legal. A Johannesburg Property Company report found 78% of outdoor advertising in the city was illegal. Enforcement began in earnest; municipal OOH revenue rose from around R4m to close to R100m a year as owners regularised. And councils are now issuing legal notices directly to brand CEOs and CMOs, regardless of who booked the placement. The report calls this its single most actionable finding: put a site-approval check into your booking workflow.
The spend vacuum
The last audited adspend figure is calendar 2023: a R44.5bn market with digital at 39.8%. There is no 2024 or 2025 edition, Nielsen is leaving the market, and Statista's numbers are paywalled. There is no public breakdown of the R26.8bn in non-digital spend into TV, radio, print and OOH for any year in the window. Every share-of-spend argument in a South African pitch deck is, on public evidence, unfalsifiable.
What the observed data does show: paid search was 73% of internet adspend, and Google took 99.4% of it. Financial services supplies roughly three in ten advertising rand. Gambling advertising reached R2.6bn in monitored rate-card value in the year to March 2025, outside the industry's own category taxonomy. PwC's forecast of digital at 74% of adspend by 2029 does not reconcile with PwC's own observed data, and the report warns against plotting the two on one line.
Macro conditions turned in 2025: inflation at a 3.2% low, household consumption up 3.56%, and load shedding gone since May 2025. Budgets set during the 2023–24 trough are calibrated to a market that no longer exists.
Digital: the biggest channel is the one you can't buy
South Africa is a high-intensity, narrow-base digital market: the connected population spends 9h37m a day online, the highest in the world, while 13.3 million people are offline entirely. Fixed home internet ranges from 44.9% of households in the Western Cape to 5.6% in Mpumalanga.
TikTok is now the fastest-growing platform on every measure. X's audience declined slowly but its advertisers left quickly. And WhatsApp is the structural peculiarity: 93.8% of social users are on it, it is the single favourite app, and it carries almost no advertising inventory. Commerce, not advertising, is the only route to monetising it.
Cookie deprecation was cancelled by Google in April 2025, ending three years of first-party data urgency. South Africa has no published independent ad-quality benchmark and no credible market size for its influencer economy. Roughly R13.9bn of the R17.7bn in 2023 digital spend was transacted through Google and Meta before counting programmatic display.
Retail media: a broadcast-scale seller in five years
Shoprite's Rainmaker Media reached an annualised run-rate above R1bn, roughly 36% of the SABC's entire advertising revenue, built from inventory the grocer already owned and 33 million loyalty members. The report is careful here: this is a juxtaposition of revenue lines, not evidence that money moved out of TV. Much of it may be trade budgets migrating into measurable media. No other South African retailer discloses meaningful numbers, and no retail media measurement standard exists.
The interregnum: every currency rebuilt at once
This is the report's spine. Most markets replace one currency at a time with a parallel run. South Africa is replacing radio and television simultaneously, has no current print readership currency, has restated OOH by 2.5×, and lost Nielsen after 38 years mid-transition. GfK's new TV currency goes live on 1 January 2027, with an all-screens view promised for 2028. Whether Nielsen's Ad Intel service survives the exit is unresolved.
Segmentation is a mess too: SEM replaced LSM years ago and shows 44% of the population in the bottom brackets where LSM showed 6%, yet the MRF still ships LSM cuts and two segmentation languages run in parallel.
The agency-side warning, quoted in the report: those who prepare will start 2027 with an advantage; those who don't will start with a measurement system they cannot interpret.
Regulation and AI: a two-year inquiry, R688m, and unenforceable remedies
The Competition Commission's Media and Digital Platforms Market Inquiry, published in November 2025, contains data that exists nowhere else. Meta throttled news referral traffic by 80% since 2020. Google's algorithms favour foreign outlets. Traffic to South African news sites fell 16% year on year.
The remedy package from Google is around R688m over five years, far below the provisional recommendation of R300–500m per year, and the Commission states plainly that its recommendations are not enforceable. Only R10.7m had landed at the time of writing. On AI licensing, the finding is unambiguous: two years of compulsory engagement with AI companies "drew a blank." No South African publisher has an AI content deal, and the report notes chatbot referrals to news total only around two million visits.
Two smaller AI stories: the draft National AI Policy was withdrawn in April 2026 because it contained AI-fabricated citations, and the IEC has gazetted a draft code requiring synthetic content to be labelled ahead of the 4 November 2026 local elections.
Language: advertising in a tongue 8.7% of the country speaks at home
English has not grown as a home language since 1996. isiZulu is 24.4% nationally and over 80% in KwaZulu-Natal; four provinces have a single language above 72%. Nine of the ten largest radio stations broadcast in an African language.
The inquiry surfaced a mechanism nobody outside it knew: Google's ad-tech stack could not serve ads in vernacular languages, and DV360 wouldn't even serve English ads on unsupported vernacular sites. When Google argued the harm was small because most SA advertising is in English, the Commission replied that English predominance online is more likely a feature of Google's restrictions than of demand. Vernacular media see roughly double the click-through rates. The report calls this the cheapest reach arbitrage in South African communications.
What it means, by role
The report closes each section with role-specific implications. Distilled:
- Media buyers: Don't sign multi-year TV deals priced off the outgoing panel. Insist every radio number is dated. Price print against paid circulation. Add an OOH site-approval check. Treat Q4 2026 as the window to learn the new TV currency.
- Media owners: The currency gap has frozen relative share; that protection ends when new data lands. Registered OOH inventory is about to become a competitive advantage. Rainmaker is the template for anyone with footfall and transaction data.
- Marketers: Fund your own outcome measurement, because exposure metrics are mid-replacement. Build a WhatsApp commerce presence rather than waiting for inventory. Your name goes on the council notice for an illegal billboard.
- PR and comms: Your 2023 media list is obsolete. Earned coverage converts to far less onward reach than 2021 benchmarks assume. Vernacular radio is systematically under-pitched.
The bottom line
The report's most memorable line is also its thesis: South Africa cannot currently see its own media market. That isn't a limitation of the research. It's the finding. Anyone planning, selling or pricing media in the country over the next eighteen months is doing so on instruments that are broken, stale, or under reconstruction, and the ones who acknowledge that will make better decisions than the ones who quote a 2018 radio number with a straight face.
Source: Acalytica, "The South African Media Landscape 2021–2026," compiled 1 September 2026. Read the full report at acalytica.com/media-landscape-2026.