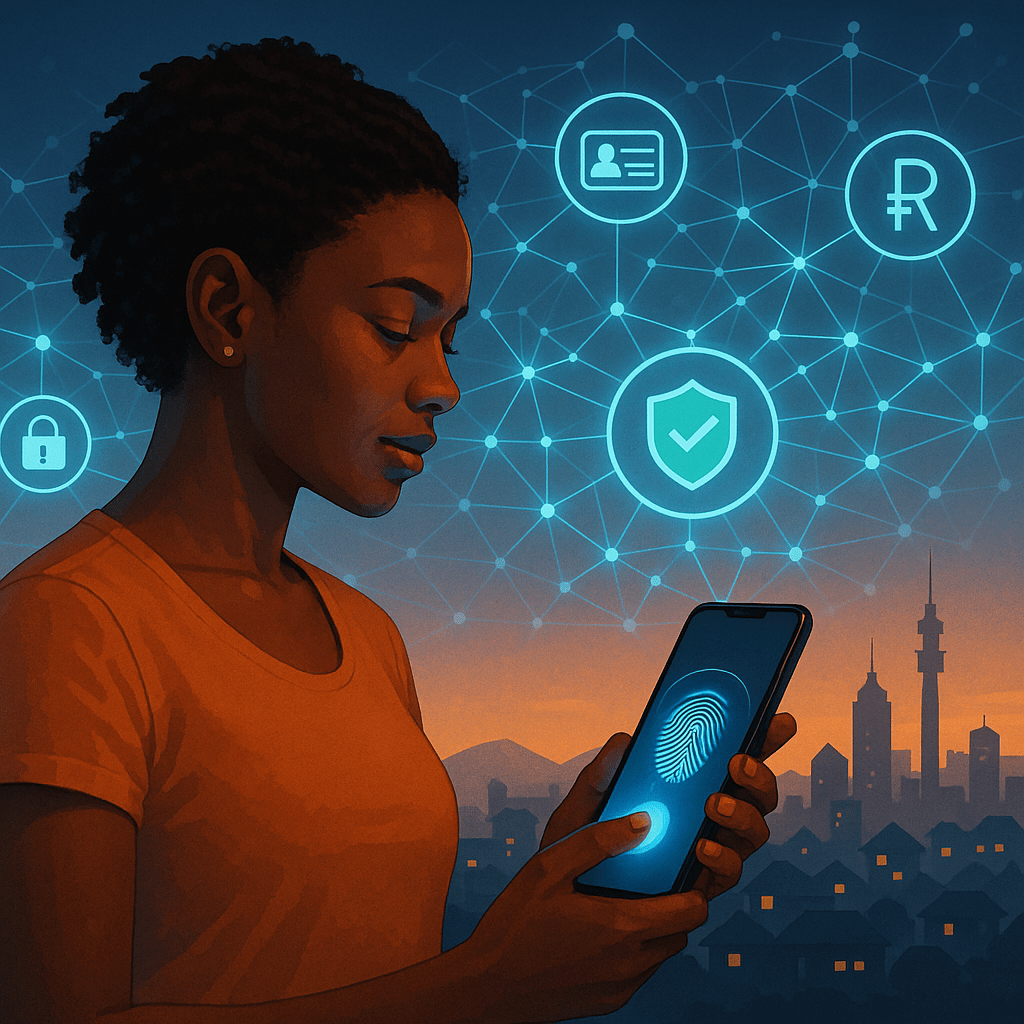
As South Africa embraces the digital economy, the nation is simultaneously facing an alarming rise in mobile and digital banking fraud. From SIM swap attacks to phishing scams and synthetic identity fraud, cybercriminals are exploiting weaknesses in fragmented systems and outdated security frameworks. The rapid digitization of financial services has far outpaced the development of unified, citizen-centric safeguards. To address this growing crisis, South Africa must urgently adopt and scale Digital Public Infrastructure (DPI)—a foundational set of open, interoperable, and secure digital systems designed to serve the public interest.
DPI is not a silver bullet, but it offers a robust and systemic approach to building trust, securing transactions, and safeguarding identities in the digital financial ecosystem. At its core, DPI comprises three critical layers: digital identity, digital payments, and data exchange systems—with optional extensions into consent management and fraud intelligence networks. These components, when implemented coherently, can form the backbone of a fraud-resistant digital economy.
One of the most effective levers DPI offers is secure digital identity infrastructure. Fraud thrives in environments where identity verification is weak, inconsistent, or siloed across institutions. In South Africa, fraudsters routinely bypass security measures through SIM swaps, stolen credentials, and forged IDs. A national, biometric-backed digital identity—verifiable in real-time and usable across platforms—can dramatically reduce the risk of impersonation and synthetic identities. When digital identity is rooted in strong authentication mechanisms such as biometrics, digital certificates, and hardware tokens, it becomes significantly harder for criminals to assume false personas or hijack legitimate accounts.
Equally vital is interoperable e-KYC (electronic Know Your Customer) infrastructure. Financial institutions currently duplicate efforts to onboard and verify customers, each maintaining isolated, inconsistent risk protocols. DPI enables the creation of a shared, trusted KYC layer, streamlining onboarding while minimizing the risks of fraudulent or duplicate accounts. With consent-based APIs and verified identity credentials, institutions can securely and efficiently validate a customer’s profile without relying on error-prone manual processes. This collective layer reduces the operational burden for banks while creating a shared defense line against identity fraud syndicates.
Fraud also flourishes in transaction workflows that rely on insecure authorization mechanisms, particularly SMS-based OTPs vulnerable to interception via SIM swaps. DPI can revolutionize this aspect through secure, interoperable digital payments infrastructure, modeled after platforms like India’s UPI. Such a system allows users to transact through tokenized approvals, biometric confirmations, or app-based authorizations—removing dependence on mobile numbers or static passwords. Payments can become not only faster and cheaper, but also inherently more secure.
Perhaps the most underutilized power of DPI lies in real-time fraud intelligence sharing. Fraud prevention in South Africa remains fragmented, with banks, telecoms, and regulators operating in silos. DPI enables secure, privacy-preserving coordination between these actors. For example, when a telco detects a suspicious SIM swap, a fraud alert can be instantly shared with banks via a DPI trust network. Similarly, behavioral patterns from one platform can inform risk scoring across the ecosystem, giving institutions the tools to act preemptively rather than reactively. This collaborative model transforms fraud detection from a point solution into a systemic safeguard.
To ensure that data sharing does not become a new risk vector, DPI includes consent frameworks that place control firmly in the hands of the user. Citizens can authorize or deny access to their data through standardized consent layers, ensuring that verification and fraud detection efforts respect individual rights and data privacy regulations. Transparency, auditability, and accountability become embedded features, not afterthoughts.
Critically, the implementation of DPI must prioritize inclusive access. Fraud disproportionately affects the digitally vulnerable—low-income individuals, the elderly, and rural populations—many of whom rely on mobile money or informal platforms with limited protection. By embedding fraud-resistant infrastructure at the public level, South Africa can ensure that the digital economy is safe for all, not just the digitally fluent.
In conclusion, the fight against digital and mobile banking fraud is not only a technical challenge—it is a systemic one. Piecemeal interventions will always lag behind increasingly sophisticated criminal networks. What South Africa needs is a coordinated, standards-based, interoperable infrastructure that protects the public by design. DPI offers that future. It is not merely a public good—it is a public necessity.
Written by the Acalytica Editorial Team — where innovation meets digital resilience.
We’re building secure, scalable digital infrastructure for Africa’s digital transformation.